I rolled into Raleigh on a Tuesday in April, the kind of spring day where you remember why people move south. The dogwoods were finishing their show, the air had that perfect soft warmth, and I was genuinely curious whether the buzz about the Triangle as a retirement destination held up in person. Everyone back home kept saying their parents or aunts had moved here. So I spent three weeks talking to longtime residents, poking around neighborhoods, checking out medical facilities, and doing the unglamorous work of figuring out what retirement actually looks like when you plant yourself here.
What struck me first wasn't the job market or the tech scene—I was past all that. It was how little the place felt like it was trying to be somewhere else. Raleigh has grown enormously over the past two decades, but it hasn't tried to become Austin or Atlanta. That matters for retirement. You're not paying Austin prices for Austin problems. You're paying something closer to middle ground—which is exactly the conversation retirees should be having.
Cost of Living: Not Cheap Anymore, But Still Reasonable
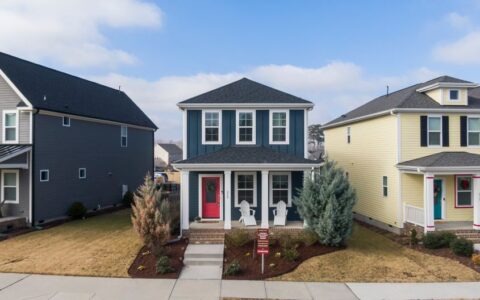
Raleigh's cost of living has risen noticeably in the past five years. Housing prices have jumped faster than anywhere else in the analysis. A decent two-bedroom house in decent neighborhoods now runs $350,000 to $500,000 on the low end—nothing like 2010, but nothing shocking for someone leaving a major coastal city either. Rentals average in the mid-$1,400s for a two-bedroom apartment, which is where you'll find a lot of active retirees who haven't bought yet.
Groceries, utilities, and dining out remain genuinely affordable. A coffee costs what it should cost. Gas prices track national trends. If you're coming from New York, Boston, or San Francisco, you'll notice the relief immediately. If you're coming from rural Missouri, you'll notice you're paying more. Healthcare costs—which matter enormously in retirement—fall in the middle of the national range. No exceptional bargain, but not a breaking point either.
One thing people often overlook: North Carolina has no sales tax on groceries, which adds up quietly over years. Property taxes are moderate, usually between 0.85% and 1% of home value depending on the county. State income tax exists and is assessed as part of the bigger picture, which I'll touch on separately.

Healthcare Access: The Real Strength Here
This is where Raleigh actually punches above its weight. Duke Health systems have a major presence, along with WakeMed, the local independent health system. Both operate well-regarded hospitals and networks of clinics spread across Wake County. I spent an afternoon at WakeMed's downtown facility—clean, reasonably modern, staffed competently. The waiting room wasn't a disaster zone.
Specialist access is solid. Cardiologists, orthopods, oncologists—the ecosystem exists. UNC is close enough (30 minutes south) for people who want specialized academic medical centers. For someone in their 60s or 70s starting to manage chronic conditions, this proximity to quality systems matters more than you'd think when you're 45. I talked to three retirees who moved here specifically because the medical infrastructure meant they could stay in place longer rather than eventually moving again to be near a major hospital.
Medicare and supplemental insurance work exactly as they do anywhere else in the country. Prescription costs track national pricing. No state-specific dramatic advantage, but no particular disadvantage either. The advantage is simply that when you need care, getting it doesn't involve a two-hour drive or a referral to a faraway center.
Weather and Climate: Four Actual Seasons
Raleigh sits in the Piedmont, which means you get real seasons without the extremes. Summers are warm and humid—mid-80s and occasionally into the 90s—but not scorching like Atlanta. Winters are chilly, averaging the mid-40s, with occasional snow that usually melts within days rather than setting in for months. Fall is legitimately beautiful. Spring arrives early compared to the Northeast.
This matters for retired people who want to actually go outside. You're not dodging 100-degree heat for three months. You're not shoveling snow in February. Mild arthritis flare-ups won't force you to abandon gardening for half the year. People with respiratory issues sometimes find the humidity in summer noticeable, but it's not Florida-level oppressive. The pollen count spikes in spring for allergies, which is worth noting if that's your particular curse.
Severe weather happens—the occasional hurricane or ice storm—but it's not a regular threat like tornado season in Oklahoma or wildfire season in California. You can reasonably plan outdoor activities year-round. That's more valuable in retirement than it sounds.

Taxes: What You Actually Need to Understand
North Carolina taxes retirement income differently depending on the source, and this is where you need to talk to an accountant who actually knows state law rather than relying on anyone's summary. Generally speaking, Social Security benefits aren't taxed. Military and government pensions have favorable treatment under state law. Traditional and Roth IRA withdrawals are taxed as regular income. 401(k) withdrawals are taxed as regular income.
State income tax rates are assessed on a sliding scale, not flat. Federal tax implications don't change because you live in Raleigh. Real estate taxes are moderate relative to the national picture. No state-level inheritance tax, which people sometimes ask about.
The honest answer is: Raleigh isn't a tax dodge. It's not Pennsylvania or Florida, where retirees flock specifically for tax advantage. But it's not a tax burden either. It sits in the reasonable middle ground. Your actual tax picture depends entirely on where your income comes from, how much of it you have, and what accounts you've built over your working life. Anyone seriously considering a move should run the numbers with a tax professional before deciding it's a factor.
Downtown and Near-Downtown Raleigh: If You Want Urban Access
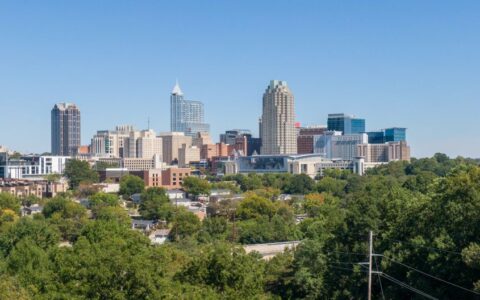
The downtown area has changed tremendously in ten years. There's a functioning brewery scene, decent restaurants clustered in specific blocks, an expanding performing arts district, and enough walkable activity that retirees who want an urban edge can actually find it. The North Carolina Museum of Art is genuinely excellent and free. The North Carolina State Farmers Market is a perennial draw. If you don't want to cook, you have options beyond chains.
Prices downtown and in near-downtown neighborhoods (like Glenwood South, Cameron Park) tend to run higher than suburban edges, but you're paying for proximity and walkability rather than paying for exclusivity. It's possible to live downtown on a modest retirement income if you're willing to live smaller—a one-bedroom condo or a modest townhouse.
The real limitation here is that downtown still feels like it's becoming something rather than being something fully formed. It's not Charleston or Savannah with centuries of identity. But that also means it doesn't have those cities' density-driven housing costs. If you want walkability and some cultural pull but don't need absolute urban gravitas, downtown Raleigh or its immediate rings are worth investigating.

Cary and Chapel Hill: The Suburbs That Feel Like Towns
Cary sits immediately west of Raleigh and has become the de facto first suburb of choice. It's consistently ranked as one of America's best places to live, which means it's become genuinely expensive—homes frequently hit $500,000 to $700,000+ in decent neighborhoods. The school systems draw families, which drives prices. But if you're past school-age considerations, what you get is an exceptionally well-maintained suburb with good amenities, solid healthcare access, and an older population of empty-nesters and active retirees.
Chapel Hill, about 30 minutes southwest, is fundamentally different. It's a college town (UNC campus dominates), which means younger energy, cultural activity beyond what Raleigh offers, but also higher density and prices that sometimes surprise people. Housing costs are generally higher than Raleigh proper. But if you want intellectual engagement, proximity to a university, live music, and the specific flavor of a college-town retirement, Chapel Hill delivers. Many retirees find the combination of cultural activity and walkable downtown (around Franklin Street) worth the premium.
Both towns have exceptional medical access through the same healthcare networks serving Raleigh. Neither feels isolated. Both benefit from the Triangle's broader economic stability. The choice between them and Raleigh proper comes down to preference: Do you want the modest urban energy of a capital city, the suburban comfort of a well-managed suburb, or the college-town flavor of academia?
Durham: If You Want Something Different
Durham gets less attention from retirement-planning articles, which is interesting because it offers genuine distinct character. It's historically a tobacco and textile town that reinvented itself around medical research and tech. That reinvention is still visibly underway—the downtown has energy but still feels like it's getting built rather than perfected, similar to Raleigh but more pronounced.
Housing is slightly less expensive than Raleigh or Chapel Hill in comparable neighborhoods. The cultural scene is strong—better music venues, more independent restaurants, a younger-skewing vibe. Duke University is here, as is Duke Health, which means exceptional medical access. For retirees who don't want a sleepy retirement and don't want mall-suburban conformity, Durham offers a distinctive middle path. You trade some polish for authenticity.
The drawback is that Durham still feels like it's earning its polish, which some people love and others find slightly rough around the edges. Public infrastructure is solid but not immaculate. Schools don't draw families the way Cary does, which keeps prices lower and the population younger. If you're past school consideration and you want distinct identity over broad appeal, it's worth more than passing thought.
Should You Move Here? The Honest Assessment
Raleigh works as a retirement destination if what you want is reasonable cost of living (for 2024), genuine medical infrastructure, mild weather that lets you stay active year-round, and a mid-sized city with enough cultural activity and restaurants to not feel left behind. It's not the cheapest retirement option in America—you'll find that in Arkansas or Kentucky. It's not the most prestigious, which appeals to some retirees and matters not at all to others.
What it does offer is balance. You're not sacrificing access to good healthcare for affordability. You're not paying colossal housing costs for the privilege of living somewhere. You're not choosing between retirement income and quality of life. For people coming from expensive metros with aging parents already here, or for people who've spent time in the Triangle and know they like it, it makes obvious sense. For people genuinely shopping for the absolute lowest retirement cost, it's not the answer. For people who need major urban walkability on a modest budget, you're paying a premium you might not need to.
The real test is spending time here for a week or two, actually staying in a neighborhood you're considering, buying groceries, visiting a doctor, sitting in a coffee shop on a weekday. Cost of living is just one variable. Fit is everything.