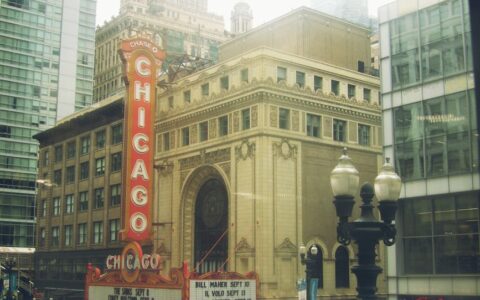
I landed in Chicago on a gray November afternoon, the kind of day that made me immediately understand why winter is the first conversation you have with anyone considering retirement here. After three weeks of renting in different neighborhoods, talking to people in their 60s and 70s who'd already made the leap, and digging into what actual monthly costs look like, I've got a clearer picture of what retirement in Chicago really means.
It's not the sleek tourist version. It's the version where you're deciding whether to spend $180 a month on a storage unit for your summer bike, or whether you're hard-core enough to keep it in your apartment. It's where you've got serious healthcare options but you're also checking the weather app obsessively from October through April. And it's where your money goes further than it does in a lot of coastal cities, but not by the margins you might think.
Cost of Living for Retirees
Figure on spending between $2,800 and $4,200 per month to live comfortably in Chicago proper, depending on the neighborhood and your appetite for eating out and entertainment. Housing is the variable. A one-bedroom apartment in a decent neighborhood runs $1,400 to $1,900 a month for rent; if you're buying, you're looking at prices that vary wildly by block—from $400,000 to well over $1 million in established retirement-friendly areas.
Groceries, utilities, and transportation are reasonable. A tank of gas, a grocery run, a decent dinner out—none of this will shock you compared to coastal cities. The property tax hit is real though. Illinois property taxes run among the highest in the nation, averaging around 0.85% of home value annually. For a $500,000 house, that's roughly $425 a month in property tax alone. It stings.
Healthcare costs are moderate. You've got the University of Chicago hospitals, Northwestern Medicine, and a dense network of clinics and specialists. Unless you're looking at major surgery or extended care, most retirees find costs align with national averages. Prescription drugs through Medicare run standard rates.
One realistic number: if you're drawing $4,000 a month and living modestly in a secondary neighborhood, you'll be fine. If you want to be in Lincoln Park or River North and eat out three times a week, you need closer to $5,500.

Healthcare Access and Systems
Chicago's healthcare infrastructure is among its strongest assets for retirees. You're not choosing between two options; you're choosing among several major hospital systems that all compete for patients and actually maintain quality standards because of it.
The University of Chicago Medical Center is world-class and has a strong geriatrics program. Northwestern Medicine operates multiple facilities and is integrated with a solid network of clinics on the North Shore and in the suburbs. Advocate and Loyola also run major operations. Walk into any of these systems and you'll find specialists—cardiologists, rheumatologists, orthopedic surgeons—without a six-month wait.
One thing I heard repeatedly from retirees who'd moved to Chicago: the primary-care appointment book fills up, but you can find someone. The city's enough of a draw that doctors stay and build practices here. Medicare Advantage plans have robust networks. Supplemental plans (Medigap) are competitively priced.
The real benefit? If you develop a condition in your 70s that needs ongoing care, you're not in a situation where your cardiologist is retiring and the next one is an hour away. The density of providers matters.
Winter Climate and What It Actually Means
Let's be direct: Chicago winters are not for everyone, and pretending otherwise is doing a disservice to anyone considering retirement here.
You're getting 28–30 inches of snow per year on average, with January lows around 22°F and occasional stretches below zero. The wind off the lake is real and not poetic. You'll need a good coat, good boots, and ideally a good attitude about staying inside three months a year. That said, people thrive here year-round. Many retirees I spoke with had spent decades away from Chicago and came back because they missed the seasons—and missed the city enough that winter was a tradeoff worth making.
The city plows aggressively and prioritizes main streets quickly. Public transit still runs. Some neighborhoods are windier and darker than others; Lincoln Park and the North Shore catch lake breeze harder than the west side or parts of the South Side. If you're buying a house, south-facing windows and a garage matter.
What I heard most often: people in their 70s who grew up in the Midwest don't mind winter. People moving from Phoenix or Florida take a year to adjust, then either lean into it or consider Florida. There's rarely a middle ground. The libraries, museums, and indoor cultural life are dense enough that winter doesn't mean isolation, but it does mean less outdoor time.
Tax Considerations at the State Level
Illinois has a flat income tax rate of 4.95%, which is moderate compared to some coastal states but higher than many Southern and Western states with no income tax. Social Security benefits are exempt from state income tax—this is significant for retirees. Pension income is also exempt. So if you're living primarily on Social Security and a pension, your state tax burden is lighter than it looks at first glance.
Property tax is the real tax burden in Illinois. As mentioned, it's steep. County assessments vary, and Cook County (which includes Chicago) runs on the higher end. A few retirees I spoke with had pushed slightly outside the city to suburbs like Evanston or Oak Park where property tax, while still high, sometimes offered a bit more breathing room per dollar of housing cost. Neither of these is cheap, but the math shifts slightly.
I'm not a tax advisor, and anyone retiring should talk to an accountant about their specific situation. But the general reality: if you're on Social Security and a pension, Illinois is less punishing than the sticker price suggests. If you're drawing heavily from investments and capital gains, the state's going to take its cut.
Lincoln Park and the North Shore
Lincoln Park is the obvious first choice for retirees, especially those with money. Tree-lined streets, the zoo and botanical garden, strong walkability, dense restaurants and cultural options, and easy access to public transit. It's expensive—rents push $1,800 to $2,200 for a one-bedroom—but you get what you pay for. The neighborhood skews younger than you'd expect, but there's a solid retiree presence, especially in single-family homes on the quieter blocks.
The North Shore suburbs—Evanston, Wilmette, Winnetka—are another class entirely. Evanston is more urban and walkable; it's got Northwestern University, which shapes culture and brings restaurants and bookstores. Housing is still steep, but slightly less than Lincoln Park proper. Wilmette and Winnetka are more residential and more expensive, with good schools (irrelevant to you, but it shapes the character of the neighborhoods) and established, quiet streets.
I spent time in Evanston and kept hearing the same thing from retirees: "I didn't want to move to the suburbs, but I came here and realized it's not actually the suburbs. It's connected to the city." The Metra commuter rail gets you downtown in 20 minutes. You've got grocery stores, doctors, restaurants, and cultural events without needing a car. It feels like a choice, not a retreat.
Pilsen and Bridgeport: Emerging Alternatives
If you want lower costs and a different vibe, Pilsen on the South Side is worth considering. It's an arts neighborhood with a strong Mexican cultural presence, good walkability, far cheaper rents ($900–$1,300 for a one-bedroom), and genuine character. You're trading some of the amenity density of Lincoln Park, but you're gaining authenticity and money in your pocket.
Bridgeport, adjacent to the south, is going through its own slow transformation. It's cheaper still, more industrial and grittier, with solid transit connections. Neither of these neighborhoods has become a retirement destination yet, which means you're not in an age-ghetto, but you're also taking on a bit more urban friction.
The calculus here: if you're 68, reasonably healthy, comfortable with city noise, and want to stretch your retirement money, Pilsen gives you real monthly savings—potentially $400–$600 compared to Lincoln Park—without isolating you. You can take the 'L' to the cultural institutions, restaurants, and medical facilities downtown. You're not getting the manicured tree-lined streets, but you're getting a neighborhood with actual life in it.
Getting Around Without a Car
This is crucial for retirees. Chicago's public transit—the 'L' and Metra trains, plus buses—is reliable enough that you don't need a car if you're willing to live in the right area. Lincoln Park, Evanston, and downtown-adjacent neighborhoods all have strong transit access. The South Side is patchier but workable.
The CTA offers a reduced fare card for seniors (65+) that cuts bus and train costs roughly in half. A monthly pass runs around $30 instead of $105. This matters on a fixed income. Metra also offers senior discounts for suburban commutes.
What I noticed: retirees who'd given up their cars all said they missed them at first, then stopped missing them within six months. One woman told me, "I save $400 a month on insurance and maintenance. I take a Lyft when I need to get somewhere outside the transit zone, and it's still cheaper than owning." In winter, the walking-in-snow factor pushes some people back to driving or living in buildings with attached parking. But in a walkable neighborhood, many retirees skip the car entirely.
The Honest Summary
Retiring in Chicago makes sense if you want an affordable major city with excellent healthcare, cultural density, and real seasons. It does not make sense if you're moving from Florida thinking you'll save money—your costs will be similar or higher once you factor in heating, and you'll spend three months wishing you'd stayed warm.
The neighborhoods and price points are real. You can retire here comfortably on $45,000 to $60,000 a year if you're willing to live modestly on the South Side or in secondary areas. You can also spend $80,000 a year in Lincoln Park and still feel the pinch from property taxes. The decision isn't about whether Chicago is affordable—it is, relatively—but about whether the trade-offs align with your priorities.
Frequently Asked Questions
How much does it cost to retire in Chicago per month
A comfortable retirement in Chicago costs between $2,800 and $4,200 per month, depending on the neighborhood and lifestyle. Housing is the biggest variable, ranging from $900 monthly rent in South Side neighborhoods like Pilsen to $1,900+ in Lincoln Park. This includes groceries, utilities, transit, healthcare, and dining out 2–3 times weekly. Property taxes are high if you own, running roughly 0.85% of home value annually.
Is Illinois good for retirement due to taxes
Illinois has a moderate 4.95% flat income tax, but Social Security and pension income are exempt from state taxation—a significant advantage for retirees. The real tax burden comes from property taxes, which are among the nation's highest. If you're living primarily on Social Security and a pension, Illinois is less punishing. If you're drawing heavily from investments and capital gains, the state will take a substantial cut.
What neighborhoods are best for retirees in Chicago
Lincoln Park and the North Shore (Evanston, Wilmette) are the traditional retirement choices, offering walkability, strong healthcare access, and cultural amenities, though housing costs are high. For budget-conscious retirees, Pilsen on the South Side offers lower rents ($900–$1,300), walkability, and access to transit and cultural institutions, with less developed senior infrastructure but lower costs.
Can you live in Chicago without a car as a senior
Yes, Chicago's public transit is robust enough for car-free living if you choose a neighborhood with strong 'L' and bus access, like Lincoln Park, Evanston, or downtown areas. Seniors 65+ qualify for reduced fares (about $30/month instead of $105). Some retirees take occasional Lyft trips and still save $400+ monthly compared to car ownership. Transit is less reliable on the South Side but still functional.
{“@context”:”https://schema.org”,”@type”:”FAQPage”,”mainEntity”:[{“@type”:”Question”,”name”:”How much does it cost to retire in Chicago per month”,”acceptedAnswer”:{“@type”:”Answer”,”text”:”A comfortable retirement in Chicago costs between $2,800 and $4,200 per month, depending on the neighborhood and lifestyle. Housing is the biggest variable, ranging from $900 monthly rent in South Side neighborhoods like Pilsen to $1,900+ in Lincoln Park. This includes groceries, utilities, transit, healthcare, and dining out 2–3 times weekly. Property taxes are high if you own, running roughly 0.85% of home value annually.”}},{“@type”:”Question”,”name”:”Is Illinois good for retirement due to taxes”,”acceptedAnswer”:{“@type”:”Answer”,”text”:”Illinois has a moderate 4.95% flat income tax, but Social Security and pension income are exempt from state taxation—a significant advantage for retirees. The real tax burden comes from property taxes, which are among the nation’s highest. If you’re living primarily on Social Security and a pension, Illinois is less punishing. If you’re drawing heavily from investments and capital gains, the state will take a substantial cut.”}},{“@type”:”Question”,”name”:”What neighborhoods are best for retirees in Chicago”,”acceptedAnswer”:{“@type”:”Answer”,”text”:”Lincoln Park and the North Shore (Evanston, Wilmette) are the traditional retirement choices, offering walkability, strong healthcare access, and cultural amenities, though housing costs are high. For budget-conscious retirees, Pilsen on the South Side offers lower rents ($900–$1,300), walkability, and access to transit and cultural institutions, with less developed senior infrastructure but lower costs.”}},{“@type”:”Question”,”name”:”Can you live in Chicago without a car as a senior”,”acceptedAnswer”:{“@type”:”Answer”,”text”:”Yes, Chicago’s public transit is robust enough for car-free living if you choose a neighborhood with strong ‘L’ and bus access, like Lincoln Park, Evanston, or downtown areas. Seniors 65+ qualify for reduced fares (about $30/month instead of $105). Some retirees take occasional Lyft trips and still save $400+ monthly compared to car ownership. Transit is less reliable on the South Side but still functional.”}}]}