I flew into Memphis on a gray February afternoon expecting the predictable narrative—cheap Southern city, blues bars, convenient retirement destination. What I found was more complicated. The moment I stepped out of the car at my hotel, I felt the weight of the Mississippi humidity even in winter, and I understood immediately why climate matters here. Over the next week, I talked to people who'd retired here, wandered neighborhoods from Germantown to South Main, checked out hospitals, grabbed coffee at places where the price tag was genuinely low, and got a clearer picture of what retirement in Memphis actually looks like.
The question isn't whether Memphis is cheap—it is. The real question is whether cheap is enough. Memphis has real advantages for retirees: no state income tax, housing costs significantly below national averages, and a food and arts scene that punches way above its weight. But it also has legitimate friction points: brutal summers, patchy healthcare infrastructure in some areas, and neighborhoods that can vary wildly block to block. If you're considering a move here, you need to know the specifics, not just the marketing.
Housing Costs and What Your Money Actually Buys
A comfortable two-bedroom house in most of Memphis runs you $250,000 to $350,000 depending on neighborhood and condition. That's roughly half what you'd pay in Nashville or Charlotte, and a quarter of what you'd drop in most of the Northeast. Rent, if that's your angle, hovers around $1,000 to $1,400 for a one-bedroom apartment in decent areas. I visited Midtown, where young retirees often cluster, and saw everything from restored Victorians in the $300K range to newer condos. The inventory moves slowly—this isn't a seller's market—which means you have time to be picky.
The catch is that lower prices correlate with older housing stock. You're buying a lot of pre-1950s homes here, which means you're budgeting for HVAC work, roof replacement, and possibly foundation issues. Property taxes are moderate by national standards but not negligible: expect to pay roughly 0.7 to 0.8 percent of your home's assessed value annually. One retiree I spoke with in Cooper-Young (the Midtown arts district) bought a 1920s bungalow listed at $275K, then spent another $25K on structural repairs before moving in. That's not unusual.
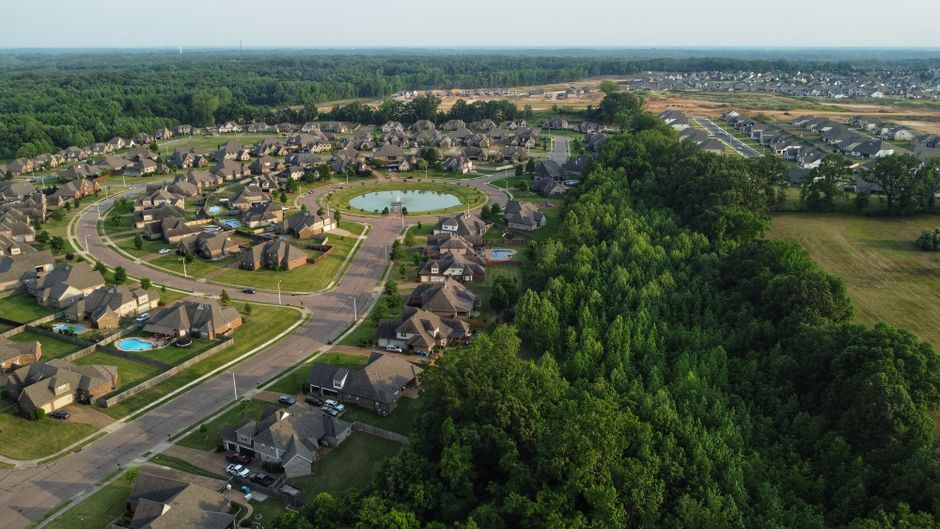
If you want new construction with minimal upkeep, Germantown and Collierville—affluent suburbs east of the city—offer planned communities and subdivision-style living. Homes there run $400K and up, which narrows the cost advantage but still undercuts most comparable markets. The tradeoff is a car-dependent lifestyle and a much more conventional suburban feel.

Groceries, Utilities, and Daily Spending
Grocery prices in Memphis are genuinely below the national average. A trip through Whole Foods or even a standard Kroger shows it immediately: produce, dairy, and proteins all cost noticeably less than in most major metros. For a couple eating modestly at home, you're looking at $250 to $350 monthly for groceries, well under the national average of roughly $400 to $500. Restaurant prices follow the same pattern—a decent dinner out costs $12 to $18 per entrée at mid-range spots, and ethnic food (Thai, Vietnamese, Mexican) is cheap and abundant.
Utilities run about $120 to $160 monthly in winter and can spike to $250 to $300 in summer when AC is running full-time. That summer bump is real and worth factoring into your budget. Internet and cable are competitive; you'll find packages around $80 to $120 monthly depending on speed and provider. Gas is affordable, though car dependency means you're buying it regularly if you're living anywhere outside Midtown or Downtown.
Healthcare: Reality and Limitations
Memphis has two major health systems: Methodist Le Bonheur Healthcare and Regional One Health. Methodist is generally considered the stronger of the two, with modern facilities and specialties concentrated around the Medical District on Madison Avenue. Regional One is technically the public hospital and serves a different demographic; quality varies depending on which clinic or service you're accessing. If you have specific healthcare needs—cardiology, oncology, orthopedics—you can find specialists here, though choice is more limited than in larger metros like Nashville or Atlanta.
The real issue isn't emergency care; it's continuity. Rural parts of Shelby County and surrounding areas have real physician shortages, especially in primary care. If you're retiring in or near Germantown, you'll have better access than if you're in a more remote part of the county. Specialists are concentrated Downtown and around Germantown, so a retiree living, say, far south of the city might face a 30-minute drive for a routine appointment.
Medicare coverage is standard, but if you're pre-65, healthcare costs can be significant. Tennessee's Medicaid program is limited compared to neighboring states—it doesn't accept the Affordable Care Act expansion, so options for lower-income retirees are narrower. Talk to a healthcare broker before you commit.

The Summer Heat Problem You Can't Ignore
July and August in Memphis are punishing. Temperatures consistently hit 90°F to 95°F, with humidity making it feel 5 to 10 degrees hotter. This isn't dry Phoenix heat; it's the kind of humidity that makes you reconsider outdoor activities. Most retirees don't mind a warm winter (January averages around 42°F), but the summer reality shapes how you actually live here. You're spending June through September inside, or near water, or awake very early or very late. That's not a dealbreaker for everyone, but it's not negligible either.
Air conditioning usage means higher summer electricity bills, and it also means constant maintenance. Units fail faster in this climate. If you have respiratory issues or heat sensitivity, you'll want to think hard about this.
The spring and fall are genuinely beautiful—mild, low humidity, perfect for walking around neighborhoods or the Shelby Farms greenway. Winter is short and mild, which appeals to retirees fleeing snow. You're trading cold weather for brutal heat, which some people love and others find restrictive.
Taxes: What You Actually Owe as a Retiree
Tennessee has no state income tax, which is the headline everyone leads with, and it's a real advantage. Social Security is tax-free. Pensions are tax-free. 401(k) withdrawals? No state tax on those either. That's a meaningful benefit compared to states like New York, California, or Virginia. If you're living on investment income or retirement distributions, this saves you 4 to 6 percent annually depending on your income level—money that stays in your pocket.
The flip side is that Tennessee relies more heavily on sales tax (9.55 percent in Shelby County including local options) and property tax to fund state services. You're not escaping taxation; you're shifting what taxes you pay. Property tax, as noted above, is moderate but not negligible. Sales tax on groceries is lower than in many states, but it exists. The net benefit depends on your specific income mix, so this isn't a blanket win—just a different shape.
Don't assume you have no state filing obligations. If you worked in another state as a recent retiree or if you have income streams tied to another state, you may still owe filing fees. Talk to a CPA before and after you move.
Germantown: Suburban Comfort With Proximity
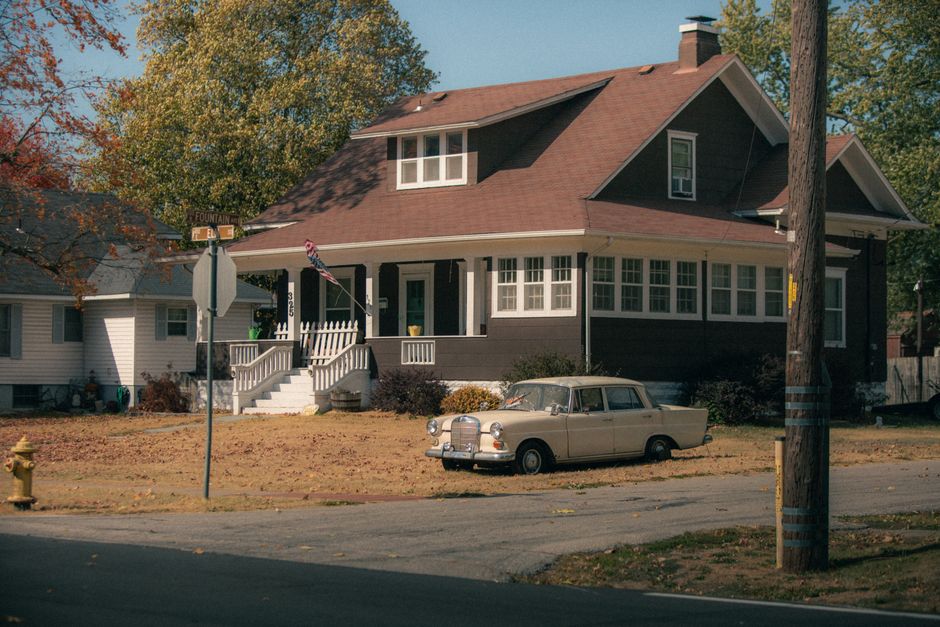
Germantown is about 20 minutes east of Downtown Memphis and has become the default retirement suburb. It's wealthy, organized, and full of country clubs and well-maintained residential streets. The high school is top-tier, which keeps home values stable and brings families into the area, so the social scene skews younger than pure-retiree communities. Housing runs $400K to $600K for good homes in established neighborhoods.
The appeal is predictable: good infrastructure, low crime relative to Memphis, and restaurants and shopping within a few minutes. The downside is that you're living a thoroughly suburban life—driving for everything, limited walkability, and a less distinctive character. If you want the cost advantages of Memphis without the urban texture, Germantown delivers. If you want walkable neighborhoods and genuine local food scenes, you'll be frustrated.
Midtown and Cooper-Young: For Retirees Who Want City Life
Midtown isn't for everyone, but it's where a lot of retirees with city orientation have landed. Cooper-Young specifically—the neighborhood bounded roughly by Cooper Avenue and Young Avenue—has walkable blocks with vintage homes, independent restaurants, art galleries, and a farmers market on Saturday mornings. Housing prices there range from $250K for a smaller Victorian to $400K for something recently renovated. You can walk to dinner, coffee, and shopping. Summer heat still dominates, but at least you're not car-dependent.
It's not polished. There's graffiti. Some streets have well-maintained homes next to rental properties in rougher condition. But there's a genuine sense of place, and the people living there actively invest in the neighborhood. One retired teacher I met had bought a two-bedroom bungalow for $265K and was slowly renovating it while working as a docent at the Memphis College of Art nearby. That's the Midtown experience—engaged, walkable, a little rawer than suburbs, cheaper than most comparable urban neighborhoods.
Safety varies by specific block. Downtown Midtown near Cooper is generally fine, especially during daytime. You want to be thoughtful about where exactly you choose and avoid certain blocks at night.
The Bottom Line for Your Situation
Memphis works best for retirees who prioritize low cost and can tolerate or actually enjoy the climate, neighborhood variety, and slightly lower healthcare specialization. If you're coming from the Northeast or California, the money difference is genuinely life-changing—you're looking at potential annual savings of $10,000 to $20,000 or more depending on your lifestyle. No state income tax compounds that over time.
It's a harder sell if you have complex healthcare needs, hate heat, or need the full array of cosmopolitan amenities. It's an excellent fit if you want to stretch your retirement dollars while remaining in a city with actual culture and food scene, and if you don't mind living in a place that's still discovering itself.
Frequently Asked Questions
Is Memphis Tennessee good for retirement?
Memphis offers significant cost advantages—no state income tax, housing 40-50% below national averages, and low daily expenses. Healthcare access is present but specialized care is more limited than major metros. Summers are extremely hot and humid. It works well if you prioritize affordability and can tolerate climate; less ideal if you need extensive medical specialization or dislike heat.
How much does it cost to retire in Memphis Tennessee?
A comfortable retirement on $40,000-60,000 annually is achievable for a couple in most Memphis neighborhoods. Housing runs $250-350K for decent homes, rent is $1,000-1,400 monthly, groceries and dining are below national average, and no state income tax saves 4-6% on retirement distributions. Utilities can spike in summer, so budget accordingly.
What are the best neighborhoods to retire in Memphis?
Germantown offers safe, well-maintained suburban living 20 minutes east of downtown, with homes starting around $400K. Cooper-Young in Midtown provides walkable, affordable urban living ($250-400K) with restaurants and galleries nearby. Downtown's South Main district appeals to adventurous retirees seeking arts and nightlife but requires comfort with urban intensity.
Does Tennessee have state income tax for retirees?
No. Tennessee has no state income tax, meaning Social Security, pensions, 401(k) withdrawals, and investment income are all tax-free at the state level. However, Tennessee relies on 9.55% sales tax and property tax, so you're not escaping taxation entirely—just shifting where it comes from. Talk to a CPA about your specific situation.
Which neighborhood would you retire in?