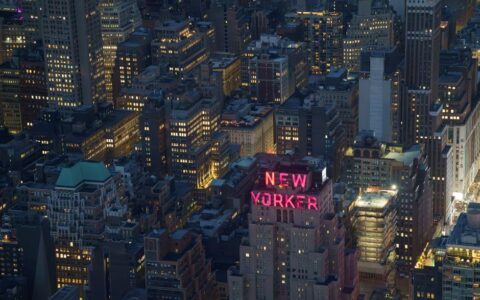
I landed at LaGuardia on a February afternoon and walked straight into the teeth of a nor'easter. The city was moving at its usual frenetic pace anyway—people leaning into the wind, still walking as if they owned the sidewalk. Somewhere in that chaos, I started wondering: who actually retires here? And should they?
It's not a silly question. New York isn't Florida or Arizona. There's no retiree migration narrative here, no communities of golf carts and early-bird specials. What there is, though, is a city that works differently for people who've already built a life here versus those moving in fresh. The answer to whether New York makes sense for retirement isn't a simple yes or no—it depends almost entirely on your money, your health priorities, and honestly, whether you can tolerate winter without resenting it.
The Cost of Living Reality
Let's not dance around this. New York is expensive. Period. A modest one-bedroom apartment in Manhattan runs $2,500 to $3,500 monthly, and that's before utilities. Brooklyn and Queens aren't the bargains they were ten years ago either. Outer boroughs like the Bronx and Staten Island offer relief—you might find a decent place for $1,500 to $2,000—but you're trading proximity and transit convenience.
If you own property outright in the city, retirement math shifts dramatically. Property taxes are steep (average around 0.8% of assessed value annually), but at least you're not paying rent. If you're coming in from elsewhere hoping to buy, expect to drop $400,000 minimum for a one-bedroom co-op in livable areas. That $500,000 retirement nest egg? It doesn't stretch the way it does elsewhere.
Groceries, meals out, entertainment—everything costs more. Electricity runs higher too, especially in winter. The real trade-off is whether proximity to museums, theaters, restaurants, and cultural events justifies the price tag. For some retirees, particularly those who worked their careers here and have no desire to move, it does. For others, the math simply doesn't work.

Healthcare Access—A Genuine Strength
If you need advanced healthcare, New York delivers. The city hosts world-class medical institutions: NYU Langone, Memorial Sloan Kettering, Columbia Presbyterian, Mount Sinai. Specialist availability is immediate, rarely waiting weeks for appointments. If you've spent forty years building relationships with doctors, or if you have complex health needs, this infrastructure matters.
Medicare coverage works here, and there's abundant private insurance options for supplemental plans. You won't be far from emergency care. The hospital density in Manhattan alone means ambulance response times are typically under five minutes.
The flip side: navigating the system requires patience and research. Not all practices take Medicare, and administrative overhead can be frustrating. But for serious, ongoing medical needs, New York's depth of specialists and high-quality facilities is legitimately one of the city's best arguments for retirement here.
Winter, Weather, and Whether You Can Handle It
New York winters are genuinely miserable four months out of the year. December through March you're facing slush, gray days, temperatures dipping to the 20s (Fahrenheit), and the constant need to maintain sidewalk footing. It's not deadly in the way a Texas ice storm might be, but it's relentless and unglamorous.
If you have mobility issues, arthritis, or respiratory sensitivity, winter is a real obstacle. Ice on sidewalks, salt damage to shoes and clothing, the psychological weight of darkness—it adds up. Many retirees here escape to Florida or the Caribbean for February and March. That's an additional cost and effort worth factoring in.
Spring, summer, and fall are genuinely excellent. Low humidity, manageable temperatures, green parks, outdoor culture fully alive. If you can afford to travel through winter or genuinely don't mind it, the other three seasons almost compensate.
State and Local Taxes—What You Should Know
New York State has income tax that maxes out around 6.85% for high earners, plus a separate city income tax (around 3.9% additional for residents). Combined, it's one of the higher state tax burdens in the country. That matters for Social Security income depending on your overall revenue picture.
Property tax rates are high relative to home values. An $800,000 home might generate $6,400 in annual property tax. If you're on a fixed income, that compounds.
Tax planning here requires actual professional advice, not internet generalizations. Some retirees benefit from New York's rules around pension income or Social Security. Others would save substantially by leaving. This is the kind of decision you make with a CPA or financial advisor familiar with multi-state retirement, not something you decide based on a travel article. What I can tell you: assume taxes will be a significant slice of retirement budget, and factor that in seriously.
Upper West Side and Upper East Side: Manhattan's Quieter Neighborhoods
The Upper West Side has long been where older New Yorkers who want to stay in Manhattan actually retire. It's not trendy or particularly young. Lincoln Center anchors the western edge, providing cultural programming year-round. The subway access (A, C, 1, 2, 3 lines) is solid though crowds are dense. Apartments run $3,000 to $4,000+ monthly for one-bedroom, and co-ops or condos require seven-figure commitments.
What you get: walkability, medical density (Roosevelt Hospital, various outpatient practices), established neighborhoods where you'll find other long-term residents. Restaurants skew toward established institutions rather than hype. There's a sense of stability.
The Upper East Side is similar, perhaps marginally more affluent. Cornell Weill Medical Center sits on the East Side, reinforcing the healthcare argument. You're paying comparable prices for marginally lower density and slightly quieter blocks.
Both neighborhoods are good if you're already embedded in New York life and want to stay but prefer less chaos than Midtown or Downtown. If you're moving to New York specifically to retire, these areas still ask a lot financially.

Park Slope, Brooklyn: A Neighborhood Option with Trade-offs
Park Slope offers what some retirees find appealing: genuine neighborhood character, Prospect Park (huge quality-of-life asset), easier accessibility than Manhattan, and slightly lower rents ($1,800 to $2,500 for a one-bedroom). The brownstone-lined streets feel more residential and less corporate than much of Manhattan.
Brooklyn hospitals exist but aren't at the specialty-depth of Manhattan's. Commuting to Manhattan for appointments adds time. The transit network is okay but not as dense as it was twenty years ago.
Park Slope attracts younger professionals increasingly, which changes neighborhood tone. Some retirees like that energy. Others find it means less peer community and higher turnover.
It's a legitimate Brooklyn option if you're willing to embrace the borough identity and don't mind the partial step-down in medical convenience. Prices are rising, though, and the gap from Manhattan narrows yearly.
Westchester Towns: When You Want NYC Closeness Without City Prices
Places like Scarsdale, Bronxville, and Hastings-on-Hudson sit on the Metro-North line, putting Grand Central Terminal in thirty to forty minutes. You're genuinely leaving the city, but not completely.
One-bedroom apartments or modest homes run 40% to 50% less than comparable Manhattan space. Winters are identical to New York's, but the pace is slower. You get actual yards and quieter streets. Healthcare depends on the town—some have good medical facilities, others require city transit for specialists.
Trade-off: you're now car-dependent for daily living, which adds cost and complexity as you age. The cultural density of the city isn't available casually anymore. It requires intention and travel to access.
For retirees who worked in New York, maintained lives here, but want residential quiet, Westchester is a legitimate middle ground. You're not truly retiring to the suburbs, but you're not paying Manhattan prices either. The commute to Manhattan doctors or entertainment is feasible, just no longer spontaneous.
The Real Question: Is It For You?
New York makes sense for retirement if several conditions align: you have adequate savings ($1.5 million-plus liquid, plus paid housing, is a rough baseline for comfortable living); you want access to world-class healthcare; you have deep social roots in the city and value proximity to culture and people; and you can handle winter without crumbling emotionally.
It doesn't make sense if you're hoping to retire on $40,000 annually, you have significant health issues requiring frequent specialist visits you can't navigate independently, or you're seeking a warm-weather, low-stress retirement.
The honest version: plenty of New Yorkers who earned their careers here retire here because moving feels like abandonment, and they can afford it. That's a legitimate reason. But there's no shame in choosing elsewhere. The city is thrilling for work and raising kids. It's punishing on a fixed income and genuinely harsh in winter. Most retirees I met who were genuinely happy here either had serious wealth insulating them from costs, or they'd been here so long that leaving felt impossible psychologically. Neither condition is universal.