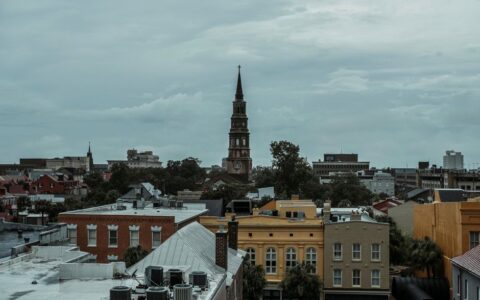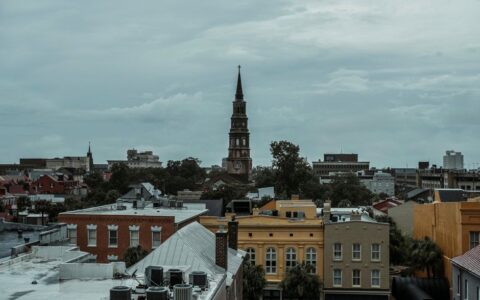
I landed at Charleston International on a humid Tuesday in May, dragging a carry-on and low expectations. I'd heard the hype—the architecture, the food, the whole genteel Southern thing—but I was here to figure out whether any of it made sense for someone actually planning to spend their last 30 years here, not just a long weekend.
The city hit different when I wasn't rushing to a restaurant reservation. Walking through neighborhoods at 10 a.m. on a weekday, I noticed retirees everywhere. Not in a theme-park way, just… living. Couples on porches, older folks at the farmers market, book clubs wrapping up at cafes. That visibility mattered. It meant the infrastructure actually had to work for people staying put, not just passing through.
The Cost of Living Question
Charleston's cost of living isn't low anymore. That ship sailed around 2015. A one-bedroom apartment downtown runs $1,500–$2,000 monthly if you're not picky about location. A modest house in an established neighborhood—nothing fancy—starts around $400,000 and climbs fast from there.
That said, it's still cheaper than most Northeastern retirement destinations, and your money stretches further outside the downtown core. Places like West Ashley or the areas around King Street are noticeably less expensive than the Historic District, yet still walkable and well-served. Grocery costs track close to the national average, and utilities aren't ruinous unless you're running air conditioning full blast eight months a year—which, let's be real, you probably will be.
Where retirees feel the pinch is property taxes and local restaurant culture. South Carolina's property tax is moderate statewide, but Charleston County assesses aggressively. And if you're someone who eats out often, the restaurant scene here will drain savings faster than you'd expect. The good news: cooking at home is entirely reasonable, and the farmers market operates year-round.

Healthcare: Real Assets and Real Gaps
Medical Park Hospital and Roper Hospital anchor the city's healthcare network, and both are reasonably equipped for routine care and most specialties. If you need a major procedure, you're in good shape. For ongoing primary care, the supply of accepting geriatric practices is adequate but not abundant—something to verify before committing to the move.
The limitation: if you develop a condition requiring specialized oncology, cardiac surgery, or other complex interventions, you're likely traveling to Shands in Gainesville or driving to Chapel Hill. That's not necessarily disqualifying, but it's real. The VA hospital serves veterans and has a solid reputation locally. For those over 65, Medicare coverage is standard, though supplemental insurance or a Medicare Advantage plan becomes essential given the specialist gaps.
Living With the Climate
The heat is oppressive June through September. Not hyperbolic—genuinely difficult for anyone with cardiovascular issues, COPD, or those simply intolerant of sustained 90+ degree heat and humidity. Air conditioning is non-negotiable, not a luxury. Cooling costs run high in peak summer.
The flip side: winters are absurdly mild. You'll wear a light jacket maybe six weeks total. No snow removal bills, no seasonal depression from endless gray days, no mobility issues related to ice and slippery surfaces. For someone with arthritis or joint pain, the consistent warmth is a real asset. Hurricane season runs June through November, and while Charleston hasn't taken a direct hit in several years, the risk exists. Storm preparedness isn't paranoia—it's basic planning.
Taxes: Keep It Simple
South Carolina taxes Social Security benefits at the federal rate but offers some exclusions if income stays below certain thresholds—something a tax advisor should confirm for your specific situation. The state income tax tops out at 7%, which is moderate compared to most regions. Property tax varies by county, and Charleston County is on the higher end, though still not brutal.
The takeaway: Charleston isn't a tax haven. If you're shopping around for retirement locations specifically for tax optimization, Florida or the Carolinas' mountain regions might offer better deals. But if Charleston is attractive for other reasons, the tax burden won't shock anyone familiar with standard U.S. retirement costs. Talk to a CPA before moving. That's worth saying twice.
Ansonborough and South of Broad: Historic Appeal With Tradeoffs
Both neighborhoods sit in the heart of old Charleston, and they draw retirees who want walkability, proximity to the water, and the prestige of Historic District living. The architecture is stunning. Restaurants, galleries, and cultural events are steps away. You can actually accomplish daily tasks on foot.
The cost is steep—houses run $600,000 to well over $1 million, and rental apartments are equally pricey. Sidewalks get crowded with tourists, especially March through May. Parking is a recurring frustration. And both neighborhoods skew toward younger retirees with solid savings or those downsizing from much larger estates elsewhere. If you value charm and don't need affordability, and you're comfortable with bustle, both are legitimate choices. Just know what you're signing up for.

West Ashley: Where Retirees Actually Live
Walk around West Ashley—the area west of the Ashley River—and you'll see more retirees per capita than anywhere downtown. Prices are lower. Homes feel less precious and more livable. You can find a three-bedroom house for $350,000–$500,000. Several planned communities cater explicitly to 55+ residents, with amenities ranging from acceptable to genuinely nice.
Trade-offs exist. It's less walkable overall; you'll need a car for most errands. The restaurant scene is serviceable but doesn't rival downtown. It's suburban in character, which some people desperately want and others find depressing. The medical complex is convenient, and traffic heading downtown isn't terrible. For retirees prioritizing budget and comfortable living over urban prestige, West Ashley deserves serious consideration.
Beaufort: A Quieter Alternative 45 Minutes Away
About 45 minutes south of Charleston lies Beaufort, a smaller town with its own historic charm and, critically, lower costs. A house in Beaufort proper might run $300,000–$450,000 for something comfortable. The pace is noticeably slower. The community is tight-knit, and retirees form visible social networks.
The drawback: fewer restaurants, less cultural programming, fewer medical specialists on-site (though Beaufort Hospital serves routine needs well). It works perfectly for someone who wants a small-town feel and doesn't need constant dining options or nightlife. Many retirees I spoke with here had moved from Charleston after a few years, preferring the quietness. That's valuable information in itself—it's not Charleston, and that's either the whole point or a dealbreaker depending on your temperament.
The Real Questions to Ask Yourself
Forget the postcard version of Charleston. The real decision hinges on specifics: Can you afford $1,500–$2,500 monthly for housing, or do you need lower? Do you have health conditions that require frequent specialist access? Does heat genuinely bother you, or is it a non-issue? How important is walkability versus car dependence? Do you want social engagement with other retirees, or do you prefer to blend into a general population?
Charleston works beautifully for retirees with moderate to solid savings, good baseline health, and either tolerance for heat or indifference to it. The infrastructure supports aging in place. The culture is genuinely welcoming to people staying long-term. But it's not a bargain, and it's not for everyone. Spend a week here in late July before deciding. Sleep in someone's guest room if you can. Eat like you live here, not like you're visiting. Then make a real call.